
Cash Envelope Budgeting By Income Life Stage For Beginners
📖 Table of Contents
When I was 23, working a part-time job and juggling student loans, I had no idea how to manage my cash flow. I'd always thought budgeting was for people with six-figure incomes or retirees, but I quickly learned that cash envelope budgeting is a lifeline for anyone, regardless of life stage or income level. What changed everything was discovering that this method could be tailored to my specific financial situation — a student with a modest income, yet still able to save and build a foundation. It wasn’t about cutting corners or giving up the things I loved; it was about finding balance and clarity.[1]
The key to mastering cash envelope budgeting by income life stage for beginners is understanding that your budget should reflect the realities of your current financial chapter. For someone like me, that meant adjusting envelopes for rent, groceries, and transportation based on my income and expenses. The method didn’t require a high salary or perfect financial habits; instead, it required honesty about what I could afford and what I needed to prioritize. It was a learning curve, but the results were tangible — I began saving consistently, reducing debt, and feeling in control of my money for the first time.
Now, I use this same method to guide others through their own financial journeys. Cash envelope budgeting by income life stage for beginners isn’t just about envelopes and cash; it’s about recognizing that your financial needs evolve as you grow. Whether you’re just starting out, raising a family, or planning for retirement, this strategy can be adapted to suit your situation. The real power of this approach lies in its simplicity and its ability to bring structure to even the most chaotic financial lives.
Why You'll Love This Cash Envelope Budgeting Method
- It’s simple and doesn’t require advanced financial knowledge.
- It fits your income level and life stage, making it adaptable.
- It helps you avoid overspending by physically limiting cash use.
- It builds financial awareness and discipline over time.
Understanding Your Income Life Stage
As of August 2026, Life stages — like being a student, young professional, new parent, or retiree — have drastically different financial needs and income levels. Understanding where you are on this journey is the first step in tailoring your cash envelope system. For example, a student with a part-time job and no dependents may have a much smaller income and fewer fixed expenses than a dual-income couple with two children.
When I was in my early 20s, I had very little income and lived paycheck to paycheck. My envelopes were tiny: $20 for groceries, $10 for public transport, and $25 for entertainment. That may sound low, but it worked for me because it forced me to be intentional with every dollar. Today, as a working professional, my envelopes are larger and more varied, but the core principles remain the same.[2]
By identifying your income life stage, you can set realistic expectations for your budget and avoid frustration. It’s not about being perfect — it’s about being honest with yourself about what you can afford and what you can’t. This self-awareness is the foundation of a successful cash envelope strategy.
Make a list of your current financial responsibilities and income sources to better understand where you fall in the life stage spectrum.
Part of our Cash envelope budgeting by income life stage guide.
Tailoring Envelopes to Your Income
The size of your envelopes should directly correlate with your income. For example, if you earn $2,500 a month and have $1,000 in fixed expenses, you can’t afford to have a $100 envelope for groceries if your income drops. This is where the cash envelope method shines — it’s about aligning your envelopes with your income to ensure you’re not overspending or under-spending in key areas.[3]
I once tried to keep a $200 envelope for dining out even though my income only allowed me to spend $100 a month on food. That didn’t last long — I ran out of money for other expenses, like rent. The lesson? Envelopes need to be realistic. If you’re earning $2,000 a month, your envelopes should reflect that, not the ideal you want to achieve.[4]
By aligning your envelopes with your income, you create a system that’s sustainable and doesn’t leave you scrambling to cover expenses. It’s a way to stay in control of your money without feeling restricted or overwhelmed.
Tailor your envelopes to your income, not your dreams.
Related: Best cash envelope budgeting income
Related: Cash envelope budgeting life checklist
Related: Cash envelope budgeting by income life stage printable
Related: Cash envelope budgeting by income life stage examples
Related: How to cash envelope budgeting income
Related: Diy Cash Envelope Budgeting By Income Life Stage
Related: Budget Cash Envelope Budgeting By Income Life Stage
Related: Cash Envelope Budgeting Beginners Guide
Setting Realistic Goals for Each Life Stage
Your life stage influences your financial goals — whether it’s saving for a house, funding your child’s education, or preparing for retirement. Your cash envelope budget should support these goals by allocating funds accordingly. For example, a young professional might prioritize an envelope for debt repayment, while a retiree might focus on medical expenses or travel.
When I was in my late 20s, my goal was to pay off student loans. My cash envelope system reflected that by allocating a larger envelope for debt payments, while keeping the rest of my envelopes small. It wasn’t perfect, but it worked. The key was not to ignore short-term needs for long-term goals — it was about finding a balance.
Setting realistic goals for your life stage ensures that your budget isn’t just a collection of numbers, but a roadmap that helps you achieve your financial dreams. This makes budgeting feel less like a chore and more like a strategy for your future.
Write down 3-5 financial goals that align with your current life stage and adjust your envelopes accordingly.
“When I was 23, working a part-time job and juggling student loans, I had no idea how to manage my cash flow.”— EnvelopeCash editors
Adjusting Your Budget as You Evolve
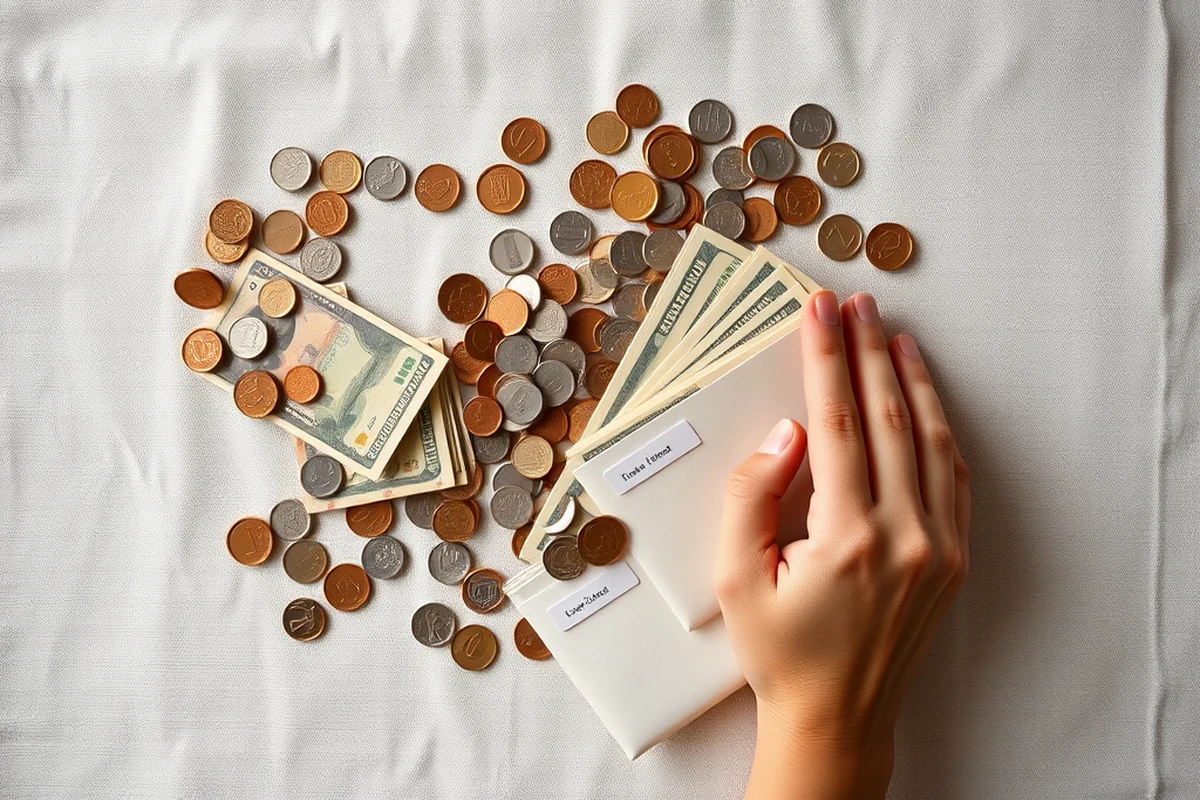
One of the most powerful aspects of cash envelope budgeting by income life stage for beginners is its adaptability. As your life changes — whether you get a promotion, have a child, or lose a job — your budget should change too. This means adjusting envelope sizes, adding new envelopes, or even eliminating some.
For example, when I had my first child, my income life stage changed dramatically. I needed to add envelopes for baby supplies, childcare, and healthcare. I also had to reduce the size of my entertainment envelope. It wasn’t easy, but it was necessary for my family’s financial stability.
By recognizing that your budget is a living, breathing system that evolves with your life, you can avoid the common pitfall of sticking to a rigid budget that no longer works for you. Flexibility is the name of the game with long-term financial health.
Building Discipline Through Physical Cash
One of the most surprising benefits of cash envelope budgeting is the discipline it brings. Unlike digital banking apps that allow for impulsive spending, physical cash in envelopes forces you to think before you spend. I’ve noticed a significant decrease in unnecessary purchases since I started using this method.
For instance, I used to overspend on coffee and takeout because it was easy to swipe my card. But when I put a set amount of cash in an envelope labeled 'Coffee & Snacks,' I found myself using it sparingly. It became a game — how long could I stretch that $30? It worked wonders for my spending habits.
The tactile experience of handling cash and seeing the money disappear as you spend it makes you more aware of your financial habits. This awareness is what leads to better financial decisions over time.
💰 Budgeting for a Tight Income
Ideal for students, part-timers, or those with irregular income. Focus on essentials and minimal envelopes.
🎯 Aggressive Payoff Strategy
For those aiming to pay off debt quickly. Increase envelope sizes for debt repayment and cut discretionary spending.
📊 Irregular Income Plan
Suitable for freelancers, gig workers, or those with fluctuating income. Use average income to set envelopes and adjust as needed.
👫 Couples' Budgeting
Great for couples with shared expenses. Allocate envelopes together, communicate regularly, and track joint goals.
🧭 Beginner-Friendly Plan
Designed for first-time budgeters. Start with 4-5 envelopes and use simple, clear labels to stay organized.
| The mistake | Why it happens | The fix |
|---|---|---|
| Not adjusting envelopes with your income or life stage. | Keeping the same envelopes regardless of your financial situation can lead to overspending or underspending in key areas. | Review your income and life stage regularly and adjust your envelopes accordingly to ensure they remain realistic and effective. |
| Using too many envelopes for non-essential expenses. | Too many envelopes can be overwhelming and lead to confusion, making it harder to track your spending. | Start with 4-5 essential envelopes and add more only when necessary. Focus on essentials like food, housing, and transportation. |
| Ignoring the 'miscellaneous' envelope. | Not having a miscellaneous envelope can lead to unexpected expenses creeping into other envelopes and causing financial strain. | Always include a small 'miscellaneous' envelope in your system to handle unexpected expenses and avoid overspending elsewhere. |
| Trying to be too strict or too lenient with envelope amounts. | Being too strict can lead to frustration and burnout, while being too lenient can result in overspending and missed financial goals. | Find a balance that works for your income and lifestyle. Be flexible but disciplined in your spending. |
Cash Envelope Budgeting By Income Life Stage For Beginners
Common Questions
How do I handle unexpected expenses with a cash envelope system?
What if I have a fluctuating income?
Can I use this method if I have a credit card?
How long does it take to adjust to this method?
References
- Foundations for Strong Families 201 - HHS ASPE (aspe.hhs.gov)
- Mental Budgeting and Consumer Decisions (bear.warrington.ufl.edu)
- Financial Wellness | Employee Health and Well-Being (colorado.edu)
- Managing Your Money, Part 2 | Consumer Financial Protection Bureau (consumerfinance.gov)
Cite this guide
EnvelopeCash (2026). Cash Envelope Budgeting By Income Life Stage For Beginners. https://envelopecash.com/cash-envelope-budgeting-by-income-life-stage-for-beginners/
Feel free to cite or share this guide.