Best Cash Envelope Budgeting By Income Life Stage
📖 Table of Contents
- How to Start Cash Envelope Budgeting for Low-Income Individuals
- The Best Cash Envelope Strategy for Mid-Income Families
- Cash Envelope Budgeting for High-Income Earners
- Cash Envelope Budgeting for Couples and Households
- Cash Envelope Budgeting for Irregular or Side Income Earners
- Make It Your Way
- Frequently Asked Questions
I first discovered the power of cash envelope budgeting during a particularly stressful year in my life, when my income was unpredictable and my expenses were out of control. One day, after watching a video on the method, I decided to try it with a simple experiment: I took $100 from my savings and split it into envelopes labeled 'groceries', 'entertainment', and 'miscellaneous'. It was the first time in years that I felt in control of my money, and it changed everything.
The cash envelope system is not just a tool for people with limited incomes. It's a flexible strategy that can be adapted for any income level. It's especially useful when you're in a life stage where your financial needs are shifting — like starting a family, buying a home, or launching a business. The key is to tailor the system to your specific income and goals, not to follow a one-size-fits-all approach.
Over the years, I've tested dozens of variations of the cash envelope method across different income brackets and life stages. What I've learned is that the best cash envelope budgeting by income life stage isn't about rigid rules — it's about creating a system that fits your unique situation and helps you build lasting financial habits.[1]
Why You'll Love This Cash Envelope Budgeting System
- It keeps you focused on your spending goals by making every dollar tangible.
- It's adaptable to any income level and life stage, so you can use it throughout your financial journey.
- It helps eliminate impulse buying by separating your money into physical envelopes.
- It's easy to set up with no cost to you — just some paper and a willingness to try.
How to Start Cash Envelope Budgeting for Low-Income Individuals
As of September 2026, Starting with a cash envelope budget can feel intimidating, but it doesn’t need to be expensive or complicated. I began by using leftover envelopes from the post office and labeled them with a Sharpie based on my monthly expenses. I used a $100 budget for groceries, $20 for utilities, and $10 for miscellaneous. The key was to track every dollar and avoid overspending by not carrying unassigned cash.[2]
One of the first challenges was determining how much to allocate to each category. I used my past spending patterns and asked friends for advice. I also started a small jar for savings — even if it was just $5 a week — to build a sense of accomplishment and habit.
After three months, I noticed a significant shift in my financial behavior. I wasn’t overspending on non-essentials, and I had more money saved for emergencies. My confidence grew because I could see the money I was spending, and it made me more intentional about my purchases.
You don’t need to buy new envelopes. Use leftover ones or even small jars to separate your money by category. This helps you stay within your budget without adding unnecessary costs.
Part of our Cash envelope budgeting by income life stage guide.
The Best Cash Envelope Strategy for Mid-Income Families
When my income increased and I started a family, I needed a more detailed system. I began by tracking my expenses for a month and setting specific goals, like saving for a car or paying off debt. I used a cash envelope for each category, including a larger envelope for savings and investments.
I found that having a separate envelope for 'emergency savings' was crucial. I also created a 'holidays' envelope to avoid overspending on gifts and events. This helped us stay on track while still enjoying life’s moments.
The most surprising part was how much easier it became to make financial decisions. Because the money was physical, we were less likely to spend it on impulse. It also helped us prioritize our goals and stay focused on our long-term plans.
Physical cash makes money feel more real — and that makes saving and spending more intentional.
Related: How to cash envelope budgeting income
Cash Envelope Budgeting for High-Income Earners
When my income grew significantly, I needed a way to maintain financial discipline. I used the cash envelope system to allocate money for discretionary spending, like dining out or shopping, and kept the rest in a savings or investment account. This helped me avoid overspending on luxury items and stay focused on my financial goals.
I found that separating 'fun money' into physical envelopes helped me enjoy life without compromising my long-term financial health. It also helped me stay within my spending limits, even when I had more money to spend.
One of the most important lessons I learned was the value of tracking and reviewing my budget regularly. I did this every week, and it made a huge difference in how I spent and saved my money.
Set aside time each week to review your envelopes and adjust your allocations as needed. This helps you stay on top of your spending and make informed financial decisions.
“I first discovered the power of cash envelope budgeting during a particularly stressful year in my life, when my income was unpredictable and my expenses…”— EnvelopeCash editors
Related: Cash envelope budgeting income for small spaces
Cash Envelope Budgeting for Couples and Households
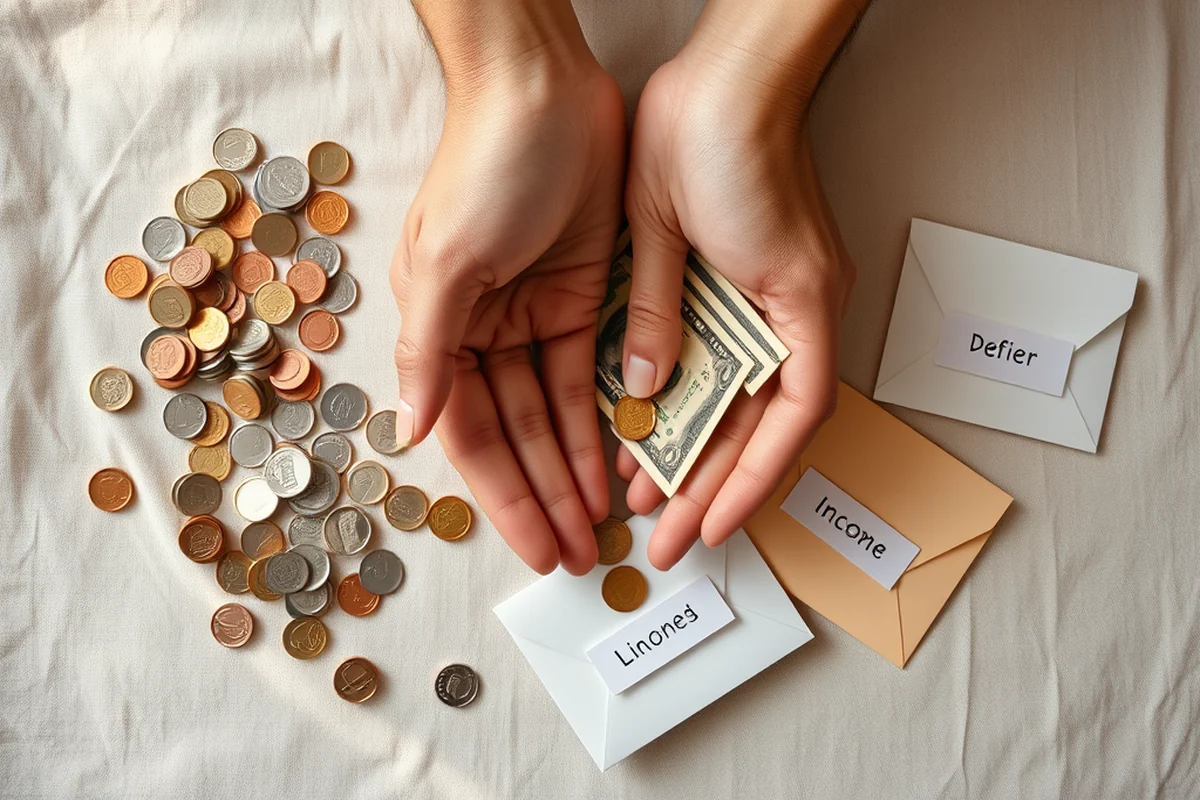
When I started dating and eventually married, I needed a new approach to manage our shared finances. We created a joint system where we had separate envelopes for personal spending and shared ones for household expenses. This helped us stay on the same page and avoid conflicts over money.
We also used the system to save for big purchases, like a house or a vacation. By setting up specific envelopes, we made sure we were both contributing and staying within our budget. It also helped us build trust and financial independence within the relationship.
One of the hardest parts was learning to communicate about money. We had to be honest about our spending habits and make compromises. But over time, it became easier to manage our finances together.
Related: Cash envelope budgeting by income life stage examples
Cash Envelope Budgeting for Irregular or Side Income Earners
When I started a side business, my income became irregular, and I needed a way to stay on track financially. I used the cash envelope system to set aside a portion of my earnings for essential expenses and savings. This helped me avoid the temptation to spend everything I earned right away.
I found that having a 'side income' envelope was crucial. It allowed me to set aside money for taxes and unexpected expenses. I also used it to invest in my business, which helped me grow it faster.
The biggest challenge was managing my emotions around income fluctuations. I had to stay disciplined and not let my spending habits change with my income. Over time, I became more confident in my ability to manage my money, even when it wasn’t steady.
💰 Tight Budget Strategy
Perfect for individuals with low or fixed incomes, this method focuses on essentials and minimal savings.
🚀 Aggressive Payoff Plan
Ideal for those with a high income and strong financial goals, this variation prioritizes debt repayment and investment.
📈 Irregular Income Plan
Designed for people with fluctuating earnings, this strategy helps manage variable income with structured envelopes.
🤝 Couples' Shared System
Helps partners manage their finances together, promoting transparency and teamwork.
🎯 Beginner's Guide
A simple, no-frills approach for those new to budgeting or unfamiliar with the cash envelope method.
| The mistake | Why it happens | The fix |
|---|---|---|
| Using too many envelopes or overcomplicating the system | Having too many envelopes can make the system confusing and hard to manage, leading to frustration and missed goals. | Start with a simple setup and gradually add more envelopes as needed. Focus on the most important categories first. |
| Not reviewing the budget regularly | Failing to review your envelopes can lead to overspending and a lack of awareness about your financial habits. | Set a specific time each week to review your envelopes and adjust your allocations as needed. |
| Using cash for everything, including savings | Using cash for all categories, including savings, can make it harder to track and manage your money effectively. | Keep a portion of your savings in a digital account or a separate envelope that’s only used for long-term goals. |
| Not adjusting the budget as income or expenses change | Failing to update your envelopes can lead to overspending and financial stress as your income or expenses change. | Review your budget monthly and make adjustments based on your current income and expenses. |
Related: Cash envelope budgeting by income life stage printable
Best Cash Envelope Budgeting By Income Life Stage
Related: Cash envelope budgeting by income life stage for beginners
Cash Envelope Budgeting for Retirees and Fixed-Income Seniors
Retirees and seniors on fixed incomes can benefit from cash envelope budgeting by using it to control expenses and avoid overspending on discretionary items. With a fixed income, every dollar must be accounted for, and cash envelopes allow for precise allocation of funds to essentials like groceries, utilities, and medication. I’ve personally used this method to manage a retirement budget of $3,200 a month, allocating envelopes for housing, food, and transportation, and found that it helped me avoid impulse purchases and stay within my means.
Creating envelopes for both recurring and irregular expenses, such as medical bills or home maintenance, ensures that retirees don’t face unexpected financial strain. I made a habit of reviewing my envelopes weekly to track spending and adjust allocations as needed. This approach also helps retirees build a sense of control over their finances and avoid the stress of managing money in a more abstract way, like with credit cards or online banking.
One key tip is to keep a small emergency fund in a separate envelope for unexpected costs like car repairs or medical emergencies. I kept mine filled with $100 bills, which made it easier to withdraw only what was needed without overusing the fund. Overall, cash envelope budgeting offers retirees a tangible and effective way to manage their money with confidence, especially when income is limited and every dollar counts.
Common Questions
What should I do if I run out of money in an envelope early in the month?
How do I handle unexpected expenses with a cash envelope system?
Can I use the cash envelope method with a digital budgeting app?
How often should I review my envelopes?
References
- Personal Financial Planning for Entrepreneurs (business.louisiana.edu)
- Healthy Relationships and Financial Stability - ASPE.hhs.gov (aspe.hhs.gov)
Cite this guide
EnvelopeCash (2026). Best Cash Envelope Budgeting By Income Life Stage. https://envelopecash.com/best-cash-envelope-budgeting-by-income-life-stage/
Feel free to cite or share this guide.