
Cash Envelope Budgeting Mistakes On A Budget
📖 Table of Contents
I remember the first time I tried cash envelope budgeting, I thought I had it all figured out. I bought a set of colored envelopes, labeled them for groceries, utilities, and savings, and felt like I was on top of my financial game. But a week later, I was standing in the grocery store, holding an empty envelope and a credit card, realizing I’d miscalculated my expenses. It was a humbling moment. It taught me that cash envelope budgeting isn’t just about having the right tools — it’s about avoiding the cash envelope budgeting mistakes on a budget that so many of us fall into.
I’ve spent the past five years helping people navigate personal finance, and one of the most common threads I see in their stories is frustration with cash envelopes. It’s not that the method is flawed — it’s that people don’t know how to use it properly. Whether they’re on a tight budget or trying to save for a big goal, cash envelope budgeting mistakes on a budget can derail progress faster than most realize.
The key to mastering cash envelopes is understanding where people commonly go wrong. I’ve made my share of errors — like underestimating how much I’d spend on impulse purchases or forgetting to account for irregular expenses — and I want to help you avoid those traps. This article is built on real-life experience, not generic advice. If you’re ready to fix your cash envelope budgeting mistakes on a budget, you’re in the right place.
Why You'll Love This Guide to Cash Envelope Budgeting Mistakes on a Budget
- You’ll learn how to avoid costly errors that waste your hard-earned cash.
- You’ll gain a clear, actionable plan for managing your finances without relying on apps or complex spreadsheets.
- You’ll discover how to customize the method to fit your unique budget and lifestyle.
- You’ll feel more in control of your money and less stressed about your financial future.
The First Step: Setting Realistic Spending Limits
As of September 2026, the most common mistake people make is setting their envelope amounts too low or too high without considering their actual habits. I once set my grocery envelope at $100 a week, thinking it was enough, but ended up running out by the second day. That’s not sustainable.[1]
To avoid this, I started tracking my spending for a full month before setting my limits. It took some time, but it was worth it. I saw where I was overspending and where I could tighten up. This approach helped me avoid running out of cash and gave me a better sense of what I needed each week.
Now, I use a simple rule: I set my envelopes at 10% more than my average spending to allow for unexpected costs. That little buffer has saved me from a lot of unnecessary stress and last-minute decisions.[2]
Before you assign cash to your envelopes, track your spending for one full month. This will help you set realistic limits that match your actual habits.
Part of our Cash envelope budgeting mistakes pitfalls guide.
The Hidden Cost of Using the Wrong Envelope Size
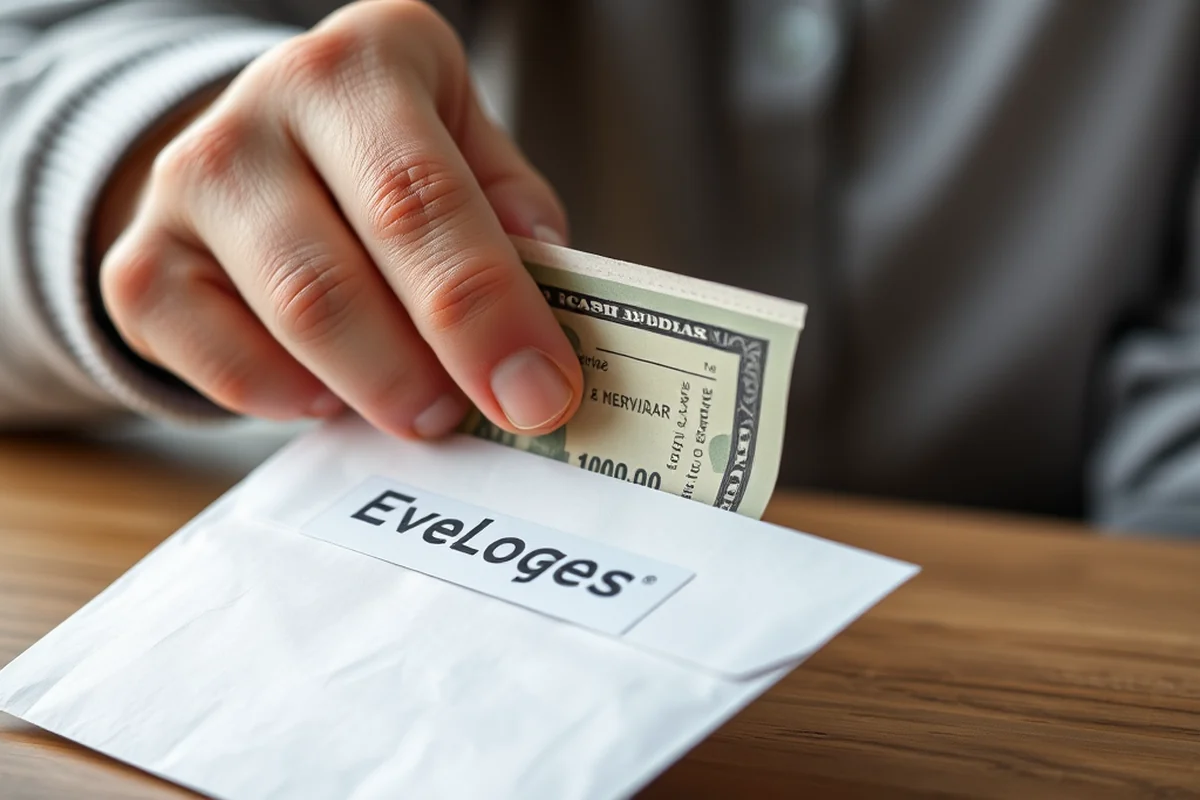
I once used small, thin envelopes for my envelopes, and it was a disaster. The bills kept falling out, and I was constantly scrambling to find where my money went. It was more work than it was worth.
After that, I switched to larger, sturdier envelopes. I now use envelopes that are thick and reinforced, which have held up well. I also label them clearly, which has helped me avoid confusion and keep track of my spending.
The right envelope size can make a world of difference in how easy or difficult the process is. It’s a small detail, but one that can save you a lot of frustration in the long run.
The right envelope size can make a world of difference.
Related: Cash envelope budgeting mistakes pitfalls that actually work
Related: Simple cash envelope budgeting mistakes pitfalls
Related: Simple cash envelope budgeting mistakes
The Overlooked Role of Emergency Funds
I used to think the emergency fund was for rainy days, not for my everyday budget. That was a mistake. One month, my car broke down, and I had no money set aside for repairs. It was a huge blow to my finances and a wake-up call.
Now, I allocate a small envelope for emergencies, even if it’s just $20 a week. It’s not much, but it has helped me cover unexpected expenses without going into debt. This little shift has made a big difference in my financial stability.[3]
Having an emergency fund is not just about being prepared — it’s about avoiding the cash envelope budgeting mistakes on a budget that can leave you scrambling when the unexpected happens.
Include a small emergency envelope in your system, even if it’s just $20 a week. It can save you from financial stress when the unexpected happens.[4]
“I remember the first time I tried cash envelope budgeting, I thought I had it all figured out.”— EnvelopeCash editors
Related: Cash envelope budgeting mistakes pitfalls ideas
Related: Diy cash envelope budgeting mistakes pitfalls
The Trap of Not Updating Envelopes
I once set up my envelopes at the beginning of the year and forgot to update them when my income changed. That led to some serious overspending and a lot of frustration.
Now, I review my envelopes every month and adjust them as needed. If I get a raise, I increase my envelopes. If my expenses go up, I adjust accordingly. This small but important step helps me stay on track and avoid financial surprises.
Updating your envelopes is a simple way to keep your budget aligned with your current financial situation. It’s a small effort with a big impact on your long-term success.
The Problem of Not Using Cash for All Expenses
I once used cash for groceries and utilities but relied on my credit card for everything else. That was a mistake. I ended up overspending on things I didn’t need and still had no control over my overall finances.
Now, I use cash for all my expenses, even small ones like coffee or gas. This helps me stay within my limits and avoid the temptation to overspend. It’s a shift in mindset, but one that has made a real difference in my financial discipline.
Using cash for all expenses is a powerful way to avoid the cash envelope budgeting mistakes on a budget that can leave you feeling out of control and overwhelmed.
💰 Tight Budget
A version of the cash envelope system tailored for people on a very limited income, with minimal setup and maximum flexibility.
🚀 Aggressive Payoff
A high-intensity envelope system for people looking to pay off debt quickly, with clear goals and strict limits.
💸 Irregular Income
A version of the cash envelope method that works well for people with fluctuating or unpredictable income streams.
👫 Couples
A shared envelope system for couples, designed to help both partners stay aligned on their financial goals and spending habits.
🌱 Beginner
A simplified version of the cash envelope method for first-timers, with step-by-step guidance and minimal complexity.
| The mistake | Why it happens | The fix |
|---|---|---|
| Setting envelopes too low without considering your actual spending. | This can lead to running out of money before the end of the month and feeling frustrated. | Track your spending for one full month before setting your envelope limits. Adjust them to match your actual habits. |
| Using the wrong envelope size or material. | This can cause money to fall out or become disorganized, making the system less effective. | Use thick, reinforced envelopes that are labeled clearly to avoid confusion and keep your money secure. |
| Neglecting to update envelopes as your income or expenses change. | This can lead to overspending or under-spending in certain categories, throwing your budget off track. | Review and adjust your envelopes every month to ensure they align with your current financial situation. |
| Not using cash for all expenses. | This can lead to overspending on non-essential items and losing control of your overall budget. | Use cash for all expenses, even small ones like coffee or gas. This helps you stay within your limits and avoid unnecessary spending. |
Cash Envelope Budgeting Mistakes On A Budget
The Pitfall of Overestimating Income
I once believed I could afford to allocate $300 monthly for dining out because I thought my income was stable, but when my paycheck dropped due to a temporary work slowdown, I was left scrambling. This mistake is common when people rely on average income figures without accounting for fluctuations. It’s crucial to use your lowest expected monthly income as the baseline for your budget, not the average or highest. This approach ensures your envelopes are based on the most conservative estimate, reducing the risk of overspending.
Many budgeters fall into the trap of assuming their income is consistent month to month, especially if they work a traditional 9-to-5 job. However, unexpected expenses, reduced hours, or even one-time bonuses can skew your cash flow. I learned this the hard way when I had to dip into savings for an emergency after miscalculating my income. To avoid this, I now track my income and expenses for at least three months before setting up my envelopes. This gives me a clearer picture of my financial reality and helps me create a more accurate budget.
Another practical step I recommend is to build a small buffer within your envelopes, especially for discretionary spending categories like dining out or entertainment. Even if you think you can afford $300 a month for these expenses, adding an extra $50 or $100 can provide a safety net when your income fluctuates. This buffer helps prevent the frustration of running out of cash for things you actually need, which can derail your entire budgeting system.
The Mistake of Ignoring the Psychology of Cash
Ignoring the psychology of cash can lead to frustration and failure in your budgeting efforts.
I once tried to use cash envelopes for every expense, including groceries and rent, without thinking about how cash affects decision-making. What I didn’t realize was that handling physical money can trigger impulsive spending, especially when I had to dig through my envelope to pay for a last-minute coffee. This led to frequent overspending and a growing sense of defeat. It’s not just about the money—it’s about how you feel when you handle it.
I later learned that cash is more effective for discretionary spending, like dining out or entertainment, where you’re more likely to be mindful of your choices. For fixed expenses, like rent or utilities, using a debit card or automatic payments can help avoid the stress and temptation that comes with cash. This shift made a huge difference in my ability to stick to my budget without feeling constantly deprived.
Now, I use cash envelopes only for variable expenses, like groceries and transportation, which are easier to monitor and control. I’ve also started keeping a small emergency fund in a separate, easily accessible envelope, which helps me avoid the temptation to dip into my fixed expenses when unexpected costs arise. This approach has made my budgeting process more sustainable and less stressful.
Common Questions
How do I handle unexpected expenses with a cash envelope system?
What should I do if I run out of money in an envelope before the end of the month?
Can I use the cash envelope system if I have a very low income?
How do I track my spending without using an app or paper?
References
- Foundations for Strong Families 201 - ASPE.hhs.gov (aspe.hhs.gov)
- FAQs—School Districts | Arizona Auditor General (azauditor.gov)
- Budgeting Tips for Beginners – The Bookshelf - Cornell blogs (blogs.cornell.edu)
- October Wellness Spotlight - University of North Dakota Blogs (blogs.und.edu)
Cite this guide
EnvelopeCash (2026). Cash Envelope Budgeting Mistakes On A Budget. https://envelopecash.com/cash-envelope-budgeting-mistakes-on-a-budget/
Feel free to cite or share this guide.