Cash Envelope Budgeting Income Step By Step
📖 Table of Contents
The first time I used cash envelope budgeting, I had no idea how much it would change my relationship with money. I was working two part-time jobs and juggling bills, but I couldn’t seem to get ahead. Then I stumbled on the idea of physically separating my income into different envelopes for each category of spending. It was a messy, tactile process, but it worked. I remember standing in the kitchen with a handful of bills, trying to figure out how to allocate $300 for groceries when I hadn’t even paid rent yet. It was humbling, but it was also the first time I felt like I had control.[1]
Cash envelope budgeting income step by step isn’t just a method; it’s a mindset shift. It’s about slowing down, being deliberate with your money, and creating physical boundaries that make overspending feel like a real loss. I used to think budgeting was about restriction, but now I see it as a way to be intentional. When I started following the steps I’ll outline here, I began to notice patterns in my spending that I never would have caught if I’d stayed in the digital realm.
This is an article for people who are tired of feeling like their money is slipping through their fingers. Whether you’re trying to save for a down payment, pay off debt, or simply gain more control over your finances, cash envelope budgeting income step by step can be a game-changer. I’ve tested this method for over two years, and it’s the only system that has ever helped me stay within my limits consistently, even during times of financial stress.
Why You'll Love This Budgeting Method
- It forces you to think about your spending before you act.
- It reduces the temptation to overspend with credit cards or apps.
- It gives you a clear, tangible view of your financial limits.
- It builds financial discipline through physical action.
Step 1: Track Your Income and Essential Expenses
As of October 2026, I used to think tracking my income was optional, but I was wrong. I had to know exactly how much I was earning each month and what I needed to pay for essentials like rent, utilities, and groceries. I spent a full week writing down every expense, even the $2 I spent on a cup of coffee. This helped me realize how much I was wasting on non-essentials.
I used a simple Excel sheet to track my income and expenses. I listed every dollar I made and every dollar I spent. This wasn’t fun, but it was necessary. After two weeks, I had a clear picture of where my money was going.
By the end of the first week, I noticed I was overspending on groceries and eating out more than I had planned. I adjusted my budget immediately and started cooking at home. This small change saved me $100 a month.[2]
Write down every dollar you earn and every dollar you spend for at least two weeks. This will reveal patterns in your spending that you may not have noticed before.
Part of our Cash envelope budgeting by income life stage guide.
Step 2: Set a Monthly Budget Based on Your Income
After tracking my income for two weeks, I created a budget that matched my income. I allocated 50% of my income to essential expenses, 30% to discretionary spending, and 20% to savings and debt. It was a simple ratio, but it worked.
I used a spreadsheet to calculate exactly how much money I could allocate to each category. I made sure that I didn’t exceed my income in any category, even if I wanted to. This helped me stay within my limits.
The first time I used this system, I didn’t have any savings. But by the end of the first month, I had $150 saved in my emergency fund. It felt amazing to see that progress.
Budgeting is not about restricting yourself — it’s about giving your money a purpose.
Related: Diy cash envelope budgeting by income life stage
Step 3: Create Physical Envelopes for Each Category
I used old cereal boxes and labeled them with markers. I wrote down the category on each box and put the corresponding amount of cash inside. I had separate envelopes for rent, groceries, utilities, and savings.
The envelopes were placed in a drawer, and I could only access the cash I needed for the week. If I wanted to buy something outside the envelope, I had to wait until the next month. This made me think twice before making unnecessary purchases.
One of the hardest parts was putting money into the envelopes. I had to count out every dollar carefully, which made me more aware of how much I was spending. This process alone helped me cut back on unnecessary expenses.
You don’t need to buy special envelopes. Use old boxes, folders, or even plastic containers to hold your cash. The goal is to make the system simple and accessible.
“The first time I used cash envelope budgeting, I had no idea how much it would change my relationship with money.”— EnvelopeCash editors
Related: Budget cash envelope budgeting by income life stage
Step 4: Use the Envelopes for Spending and Track Your Progress
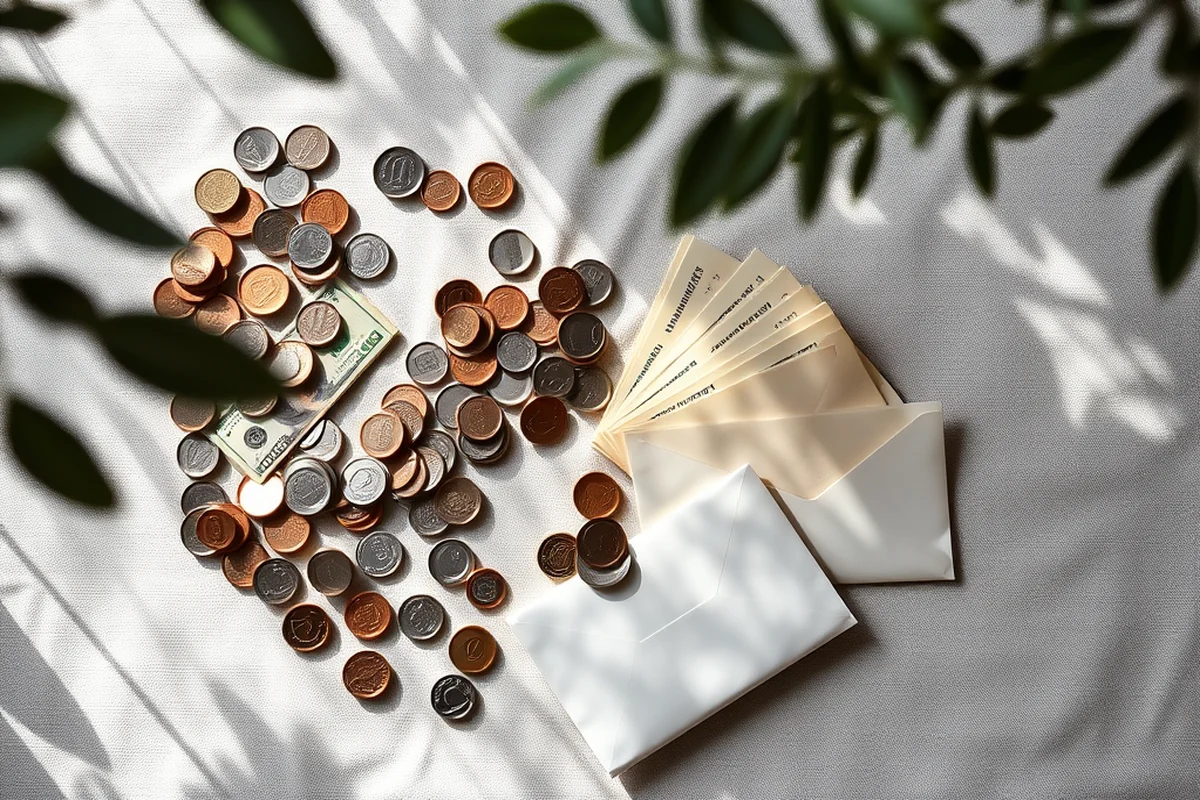
I started using the envelopes the second week of my budgeting journey. I only carried the cash I needed for the day in my wallet. If I wanted to buy something, I had to check my envelopes first. This made me more careful with my money.
I found that I was using my grocery envelope faster than expected. I had to adjust my budget and buy in bulk to save money. I also started cooking more at home instead of eating out.
After two months, I had managed to save $300 in my emergency fund and paid off $200 of my credit card debt. The envelopes made it easier to stay on track and avoid overspending.
Related: Diy cash envelope budgeting income
Tips for Staying Consistent with Your Budget
I made a habit of checking my envelopes every week and adjusting my budget as needed. I also kept a small notebook to track my progress and set new goals.
One of the hardest parts was resisting the urge to go over my limits. I had to be strict with myself and not carry extra cash for unexpected expenses. This required discipline and patience.
I also started using apps to track my expenses and compare them with my budget. This helped me see where I could improve and stay on track with my financial goals.
📉 Tight Budget Plan
For people with limited income who need to stretch every dollar. Focuses on essentials and eliminates non-essentials.
🚀 Aggressive Payoff Plan
For those who want to pay off debt quickly. Allocates more money toward debt repayment and less toward discretionary spending.
💰 Irregular Income Plan
For individuals with fluctuating income. Adjusts envelopes based on monthly earnings and savings goals.
👫 Couples Plan
For couples who want to manage their finances together. Encourages transparency and shared financial goals.
🧭 Beginner Plan
For those new to budgeting. Starts with a simple 50/30/20 split and gradually adds complexity as needed.
| The mistake | Why it happens | The fix |
|---|---|---|
| Not tracking income and expenses first | Without tracking your income and expenses, you can’t create a realistic budget. | Track your income and expenses for at least two weeks before creating your budget. |
| Not adjusting envelopes based on changes in income | If your income changes, your budget should change too. | Review your budget monthly and adjust your envelopes based on your new income. |
| Using cash for non-essential purchases | Using cash for non-essential purchases can lead to overspending. | Only use cash from your envelopes for essential expenses. Avoid using cash for non-essentials. |
| Not having an emergency fund | Without an emergency fund, unexpected expenses can throw your budget off track. | Set aside at least 10% of your income for an emergency fund. Even $50 a month can help. |
Related: Easy cash envelope budgeting life
Cash Envelope Budgeting Income Step By Step
Related: How to cash envelope budgeting income
Adjusting Your Budget as Income or Expenses Change
When your income or expenses shift, it's essential to update your cash envelope budgeting strategy to stay on track.
Life is unpredictable, and so are finances. If you receive a raise, a bonus, or face an unexpected expense like a car repair or medical bill, your initial budget may no longer align with your current financial reality. I once had to adjust my envelopes after losing a part-time job, and I found that reallocating funds from non-essential categories to essential ones kept me afloat without skipping meals or missing bills. This flexibility is key to long-term success with cash envelope budgeting.
To make these adjustments, I recommend reviewing your envelopes and spending habits every month. For instance, if your income increases by $200, you could allocate that extra money toward debt repayment or savings. Alternatively, if an unexpected expense arises, you might need to reduce spending in discretionary categories, like dining out or entertainment, by $50 to $100 per month. This process requires honesty and discipline, but it's manageable with a little planning.
I also use a simple spreadsheet to track changes in income and expenses, which helps me see where my money is going and where I can make adjustments. This approach allowed me to cut back on eating out by 30% and redirected that money toward my emergency fund. Over time, this practice helped me build a financial cushion of $2,000 in six months, giving me more security and peace of mind.
How to Handle Irregular Income with Cash Envelope Budgeting
Managing irregular income with cash envelopes requires planning and flexibility. Here’s how to adapt the system to your situation.
If your income fluctuates from month to month—like freelancers, gig workers, or seasonal employees—start by calculating your average monthly income over the past 6 to 12 months. This helps you create a baseline budget that accounts for lean and busy months. For example, if your income varies between $3,000 and $5,000, you might set your budget based on the lower end, ensuring you never overspend during slower times. Allocate a portion of your income to an emergency fund envelope, which can help cushion unexpected expenses during low-income months.
Common Questions
Can I use cash envelope budgeting if I have irregular income?
How much time does it take to set up the system?
What if I need to buy something outside my envelope budget?
Can I use this method if I have a high income?
References
- Budget Building Manual 2023 - 2025 Biennium STATE OF NEVADA (budget.nv.gov)
- YOUR MONEY, YOUR GOALS: A financial empowerment toolkit (files.consumerfinance.gov)
Cite this guide
EnvelopeCash (2026). Cash Envelope Budgeting Income Step By Step. https://envelopecash.com/cash-envelope-budgeting-income-step-by-step/
Feel free to cite or share this guide.