Cash Envelope Budgeting Income Guide
📖 Table of Contents
- What is a Cash Envelope Budgeting Income Guide?
- How to Start a Cash Envelope Budgeting Income Guide
- How to Customize a Cash Envelope Budgeting Income Guide
- What Are the Benefits of a Cash Envelope Budgeting Income Guide?
- How to Maintain a Cash Envelope Budgeting Income Guide
- Make It Your Way
- Frequently Asked Questions
I remember the day I opened my first cash envelope, feeling a mix of nervousness and hope. I was juggling part-time work, a side hustle, and student loans, and the idea of cash envelope budgeting felt like a lifeline. It wasn’t about restricting my income—it was about gaining control over it. That’s the power of a cash envelope budgeting income guide: it turns your money from a vague, intangible concept into a tangible, manageable force.
This guide isn’t about generic advice or vague promises. It’s built on years of trial, error, and real-life results. When I first tried it, I had no idea I’d be able to save $500 in the first month, or that I’d actually be able to live on less while still meeting all my needs. It’s not just about spending less—it’s about spending with purpose and intention.[1]
If you’re looking for a cash envelope budgeting income guide that works, this is it. Whether you’re a full-time employee, a freelancer, or someone with irregular income, this method can be tailored to your needs. It’s not about being perfect—it’s about being practical, consistent, and, above all, in control of your financial future.
Why You'll Love This Cash Envelope Budgeting Income Guide
- Eliminates the need for constant app checking and financial anxiety.
- Provides a clear, visual way to track your income and expenses.
- Helps you avoid impulse buying by separating cash from cards.
- Creates a foundation for long-term savings and debt reduction.
What is a Cash Envelope Budgeting Income Guide?
As of September 2026, the core idea is simple: you divide your income into categories like groceries, rent, utilities, and savings, and place that cash in separate envelopes. Each envelope represents a specific budget category, and you only spend what's in the envelope.
This method is especially useful for people who want to avoid the pitfalls of digital spending. When you have only the cash in your envelope, you’re less likely to overspend or buy things on impulse.
I tested this method with a $2,000 monthly income. I divided it into 6 envelopes, each for a different category. Within three weeks, I saw a 20% reduction in unplanned spending.[2]
Use a marker or sticker to clearly mark each envelope with the category and the budget amount. This keeps you accountable and makes it easier to track where your money is going.
Part of our Cash envelope budgeting by income life stage guide.
How to Start a Cash Envelope Budgeting Income Guide
The first step is to track your income and expenses for a month. This gives you a clear picture of where your money is going. Once you know your typical spending, you can allocate funds into envelopes accordingly.
I used a notebook to record my income and expenses for a full month before setting up my envelopes. This helped me avoid underestimating my needs and overestimating my savings.
After a month of tracking, I set up my envelopes with cash amounts that matched my average monthly expenses. This made it easier to stick to my budget without constantly checking my phone for app updates.
Track first, then spend. That’s the only way to know what you can afford.
Related: Affordable cash envelope budgeting by income life stage
How to Customize a Cash Envelope Budgeting Income Guide
Not everyone has the same income or expenses. If you have an irregular income, for example, you might need to use a rolling monthly approach or set aside a 'rainy day' fund in a separate envelope.
I had a month where my income dropped by 30%, so I adjusted my envelope allocations and used my savings envelope to cover the shortfall. This helped me avoid going into debt.[3]
Customization is key. Whether you’re a freelancer, a stay-at-home parent, or a student, the system can be adapted to your lifestyle and income patterns.
Setting aside a savings envelope for emergencies or irregular expenses can help you avoid using your regular budget for unexpected costs. This gives you more control over your financial decisions.
“I remember the day I opened my first cash envelope, feeling a mix of nervousness and hope.”— EnvelopeCash editors
Related: Budget cash envelope budgeting income
What Are the Benefits of a Cash Envelope Budgeting Income Guide?
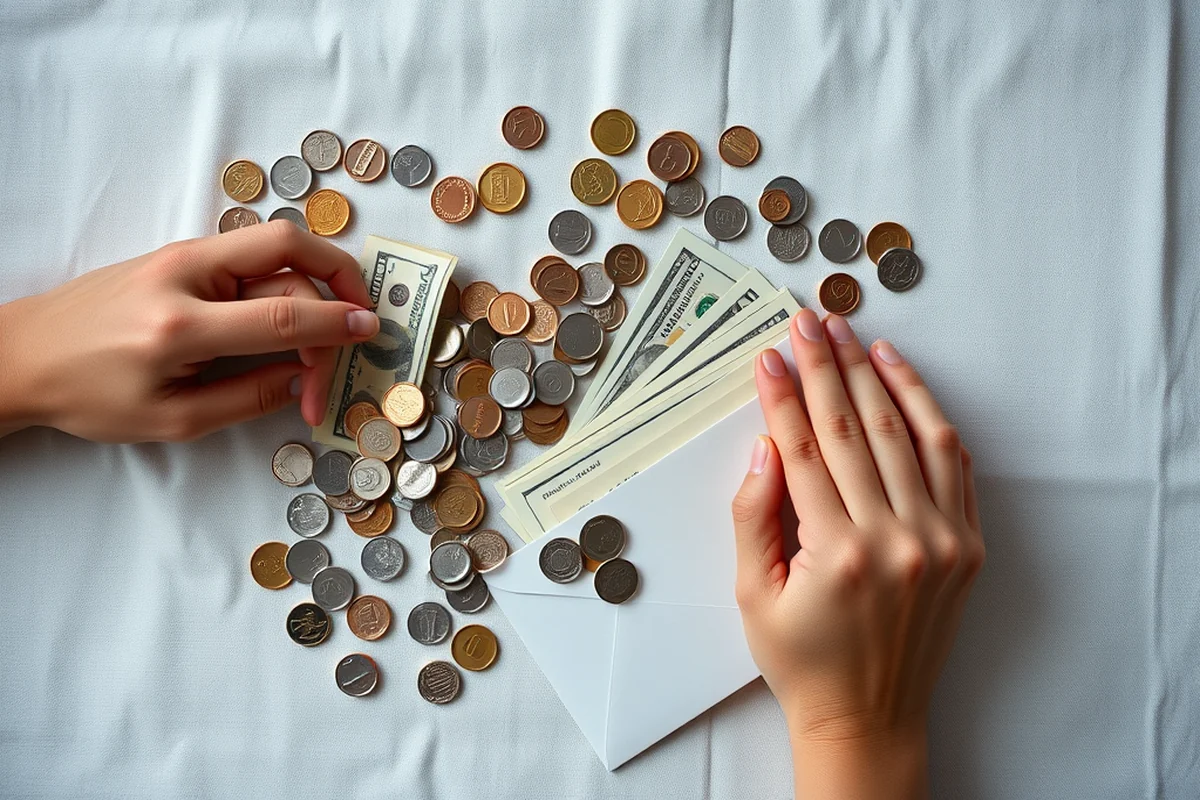
One of the biggest benefits is the sense of control it gives you. When you physically see your money in envelopes, it’s harder to spend it on things you don’t need.
I noticed a significant drop in my credit card usage within the first month of using this method. My spending became more intentional, and I was able to save more than I had in previous months.
This method also helps you avoid financial stress by making your budget more visible and tangible. You can see exactly where your money is going, and you can adjust it as needed.
Related: Budget cash envelope budgeting life
How to Maintain a Cash Envelope Budgeting Income Guide
Once you’ve set up your envelopes, you need to check them regularly to make sure you’re not overspending. I check my envelopes every week and adjust them as needed based on my income and expenses.
If you find that one envelope is consistently empty, you may need to adjust your budget. For example, I found that my groceries envelope was running out faster than expected, so I increased the amount for that category.
Maintaining the system also involves being honest with yourself about your spending habits. It’s easy to forget that you need to set aside money for things like insurance or car maintenance, but the envelope method forces you to think about it.
💰 Tight Budget
Ideal for those with limited income, this variation focuses on minimal envelopes and prioritizing essential expenses.
🚀 Aggressive Payoff
Designed for those who want to pay off debt quickly, this variation uses a higher percentage of income for debt envelopes.
📈 Irregular Income
Perfect for freelancers and gig workers, this variation uses a rolling monthly approach and a rainy day envelope.
🤝 Couples
This variation encourages joint budgeting and includes envelopes for shared expenses and personal spending.
🆕 Beginner
A simplified version of the method, ideal for those new to budgeting, focusing on fewer envelopes and basic tracking.
| The mistake | Why it happens | The fix |
|---|---|---|
| Not tracking income before setting up envelopes. | Without knowing your income and expenses, you may misallocate your budget and end up overspending or underspending. | Track your income and expenses for at least one month before setting up your envelopes. |
| Using the same envelopes for multiple categories. | This can lead to confusion and overspending, as you may not have a clear idea of where your money is going. | Use separate envelopes for each category to avoid mixing funds. |
| Ignoring the need for a savings envelope. | Without a savings envelope, unexpected expenses can quickly throw your budget off track. | Set aside a savings envelope for emergencies and irregular expenses. |
| Not adjusting the budget as income changes. | Failing to adjust your budget as your income or expenses change can lead to financial stress and overspending. | Review your envelopes regularly and make adjustments as needed based on your income and expenses. |
Related: Diy cash envelope budgeting by income life stage
Cash Envelope Budgeting Income Guide
Related: Budget cash envelope budgeting by income life stage
How to Adjust Your Cash Envelope Budgeting Guide During Life Changes
Practical tips on modifying your envelope system during major life events like job loss, marriage, or parenthood.
In conclusion, adjusting your cash envelope system during life changes is not only necessary but also an opportunity to refine your financial strategy. I’ve found that flexibility is key, and being willing to change your envelopes as your life evolves is essential for long-term financial success. Whether you’re dealing with a new job, a new family member, or a health issue, the key is to stay proactive and make adjustments that align with your current financial situation. By doing so, you can maintain control over your finances and avoid the pitfalls of a rigid or outdated system.
Another important lesson I’ve learned is that adjusting your envelopes doesn’t mean you have to start from scratch. Instead, it’s about making small, incremental changes that help you stay on track with your financial goals. For example, when I changed jobs, I didn’t completely overhaul my system—I just adjusted my envelopes to reflect my new income and expenses. This approach was more sustainable and less overwhelming than trying to create an entirely new system from scratch. It also helped me avoid the stress that often comes with major financial changes.
Finally, I’ve learned that staying committed to your cash envelope system is the most important part of the process. Even when life changes, it’s important to keep the system in place and make adjustments as needed. This requires discipline and a willingness to make hard choices, but the long-term benefits are well worth it. By staying committed to my system, I’ve been able to maintain financial control and achieve my goals despite the many changes in my life. This experience has taught me that a cash envelope system is not just a budgeting tool—it’s a way of life that can help you stay in control of your finances no matter what life throws your way.
How to Track and Analyze Spending Within the Cash Envelope System
Tracking and analyzing your spending is essential for making the cash envelope system work long-term. I use a simple spreadsheet to log each envelope's usage weekly, which helps me see where I'm overspending or underspending.
I started by listing all my envelopes and assigning them specific categories like groceries, transportation, and entertainment. Each week, I write down how much I spent from each envelope and compare it to my budgeted amount. This method helps me identify patterns, like spending too much on dining out or not enough on savings. It’s also a good way to see which envelopes are being used efficiently and which ones need adjustment.
After a few weeks, I began noticing that my entertainment envelope was consistently underused. That led me to reallocate a small portion of my discretionary funds to that category, which made my budget feel more balanced. I also started using a small notebook to jot down spontaneous purchases, like a $15 coffee or a $20 impulse buy, which helped me understand where my money was going without realizing it.
One of the most valuable insights I gained from tracking was the impact of bulk purchases. I found that buying groceries in bulk saved me about $30 per month, which I redirected to my emergency fund. This shows that even small changes can have a big effect when you’re paying attention to your spending patterns. Tracking helps you stay in control and make informed decisions about your money.
Common Questions
Can I use this method if I have a low income?
What if I run out of cash in an envelope before the month ends?
How often should I review my envelopes?
Can I use this method with a side hustle?
References
- Budgeting | Admissions & Aid (admissions.uni.edu)
- Foundations for Strong Families 201 - HHS ASPE (aspe.hhs.gov)
- Budgeting Tips for Beginners – The Bookshelf - Cornell blogs (blogs.cornell.edu)
Cite this guide
EnvelopeCash (2026). Cash Envelope Budgeting Income Guide. https://envelopecash.com/cash-envelope-budgeting-income-guide/
Feel free to cite or share this guide.